
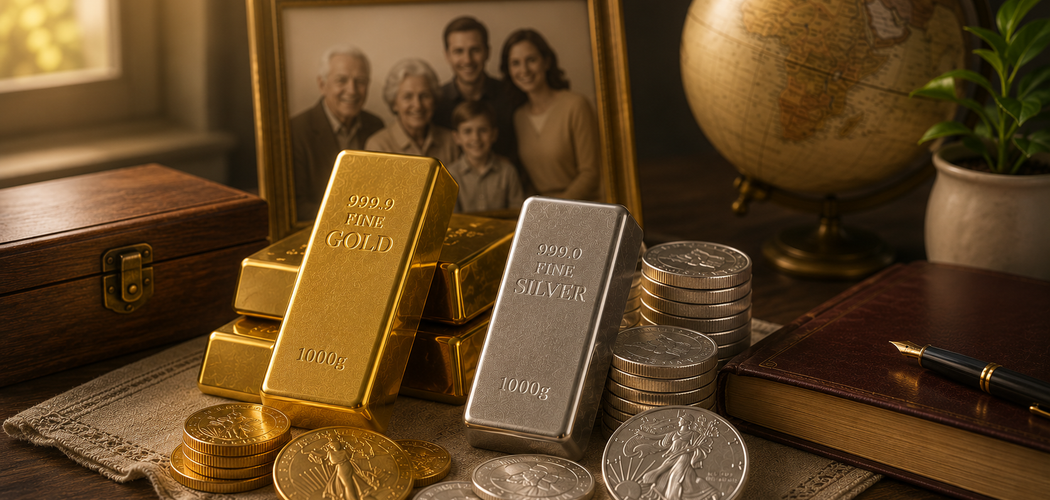
Building wealth is one achievement. Preserving it and transferring it successfully to future generations is another. Families must consider inflation, taxes, investment risk, estate planning, and changing economic conditions. For some investors, generational wealth with gold can form one part of this long-term strategy.
Gold has several characteristics that make it interesting for wealth transfer. It is durable, globally recognized, relatively compact, and not dependent on the success of one company. Physical bullion can also remain usable for decades when stored properly.
However, gold alone does not create a complete legacy plan.
Unlike businesses, stocks, or rental property, physical gold does not produce income. Its market price can also decline for long periods. Moreover, poorly documented bullion can create problems for heirs.
Therefore, families should view gold as one component of a diversified financial structure.
The objective is not simply to leave behind valuable assets. Instead, a strong legacy plan should make those assets understandable, accessible, secure, and useful to the next generation.
What Is Generational Wealth?
Generational wealth consists of assets transferred from one generation to another.
These assets can include property, businesses, stocks, bonds, cash, retirement accounts, insurance benefits, intellectual property, and precious metals.
The goal is usually broader than leaving an inheritance.
Well-planned generational wealth can provide future family members with financial stability, education opportunities, business capital, housing support, or greater freedom to pursue long-term goals.
However, wealth can disappear quickly without proper management.
Poor investment decisions, excessive spending, family disagreements, taxes, debt, and missing documentation can reduce an inheritance.
Therefore, building generational wealth with gold should involve more than accumulating coins or bars.
Families also need a clear plan for ownership, storage, records, inheritance, and eventual decision-making.
Why Gold Appeals to Long-Term Families
Gold has survived enormous changes in the global economy.
Currencies have changed. Governments have risen and fallen, while industries have transformed.
Yet gold continues to trade globally.
This durability makes it attractive to investors thinking beyond one economic cycle.
Physical gold also differs from financial claims.
A stock represents ownership in a business. A bond represents a debt obligation. Bank deposits depend on financial institutions and the applicable legal framework.
A gold bar is a tangible asset.
However, this distinction should not be exaggerated.
Physical ownership removes some risks while introducing others, including theft, storage expenses, transaction spreads, and price volatility.
Gold’s value within a family portfolio comes primarily from diversification and durability rather than guaranteed appreciation.
Gold Can Help Diversify Family Wealth
Concentrated family wealth can create significant risk.
Imagine a family whose entire net worth comes from one business.
If that company fails, the family’s financial security may deteriorate rapidly.
The same problem can occur with one property market or a concentrated stock portfolio.
Diversification spreads exposure across assets with different characteristics.
Gold can contribute because its price responds to factors such as real interest rates, currencies, central bank demand, geopolitical uncertainty, and investor sentiment.
These drivers differ from corporate earnings or rental income.
Therefore, generational wealth with gold may help reduce dependence on one specific economic outcome.
Diversification does not guarantee protection from losses. Instead, it prevents the family’s entire financial future from relying on a single asset.
Gold May Help Address Purchasing-Power Risk
Inflation can gradually reduce the purchasing power of money.
This effect becomes particularly important when families plan across several decades.
An inheritance that appears substantial today may provide much less purchasing power in the future if prices rise significantly.
Gold is often considered a potential store of value because its supply cannot be expanded as easily as modern currency.
Mining additional gold requires exploration, investment, equipment, labor, and time.
However, investors should avoid describing gold as a perfect inflation hedge.
Its price does not move directly with consumer prices.
Gold can decline during inflationary periods, especially when real interest rates rise.
Therefore, it should complement other long-term assets rather than serve as the family’s only defense against inflation.
Gold Is Durable and Compact
Physical durability is one of gold’s practical advantages.
Gold does not rust like many metals.
Properly stored bullion can remain intact for generations.
Gold also stores significant value in a relatively small physical space compared with many other tangible assets.
Silver provides an obvious comparison.
Both metals can support diversification, but storing the same monetary value in silver usually requires much more space.
Property creates even greater physical responsibilities.
Buildings require maintenance, taxes, insurance, and management.
Gold avoids many of those ongoing physical requirements.
Still, secure storage remains essential.
Families considering generational wealth with gold need to plan how bullion will remain protected while still being accessible to authorized heirs.
Physical Gold Requires Secure Storage
Owning bullion directly creates responsibility.
Some investors prefer home storage because they maintain immediate physical control.
However, home storage can create theft and security risks.
A quality safe may help, but it does not eliminate those risks.
Professional vaulting provides another option.
Specialized facilities may offer stronger security and insurance arrangements, although fees can reduce long-term returns.
Bank safe-deposit arrangements may also be available depending on the jurisdiction and institution.
Families should compare access, insurance, privacy, cost, and inheritance procedures.
The cheapest storage method is not automatically the best.
Likewise, the most secure arrangement becomes problematic if heirs cannot legally locate or access the assets when needed.
Documentation Is Essential for Heirs
Gold hidden without documentation can become lost wealth.
Imagine someone accumulates valuable bullion for decades but tells nobody where it is stored.
After that person dies, family members may not know the gold exists.
Even if they discover it, they may struggle to determine purchase prices, authenticity, or ownership history.
Therefore, records are essential.
Families should document what they own, when it was purchased, the cost, and where relevant records are stored.
Sensitive storage details should remain secure.
However, an executor, trustee, attorney, or other appropriate person may need instructions explaining how authorized beneficiaries can locate the assets.
A successful generational wealth with gold strategy balances privacy with recoverability.
Keep Purchase Records Organized
Receipts and transaction records can help establish acquisition costs.
They may also support tax reporting, insurance claims, estate administration, and future sales.
Records should be updated whenever bullion is purchased, transferred, or sold.
Estate Planning Should Include Precious Metals
Owning gold does not automatically determine who receives it after death.
Inheritance laws vary by jurisdiction.
Therefore, bullion should be considered within the family’s broader estate plan.
A will may specify beneficiaries.
Trusts or other structures may also be appropriate depending on local laws, family circumstances, and the size of the estate.
Investors should avoid informal assumptions such as believing family members will simply divide the bullion fairly.
Ambiguity can create disputes.
Clear documentation can reduce uncertainty.
Professional legal and tax advice may be valuable for significant holdings because inheritance, capital gains, probate, and reporting rules differ substantially between locations.
The objective is to make the transfer orderly rather than leaving heirs to solve complicated ownership questions.
Consider How Gold Will Be Divided
Physical assets create practical inheritance questions.
Suppose a parent owns one large gold bar and has three beneficiaries.
The bar cannot easily be divided physically without changing the product.
The beneficiaries could sell it and divide the proceeds.
One heir could also purchase the others’ interests.
Alternatively, the owner could accumulate smaller denominations that are easier to distribute.
This does not mean small products are always better.
Smaller bars and coins may carry higher premiums.
Therefore, families need to balance purchasing efficiency with future flexibility.
Planning ahead can make generational wealth with gold easier to transfer without forcing heirs into decisions they did not expect.
Teach Heirs What They Are Receiving
Financial education can be as important as the inheritance itself.
Someone who receives gold without understanding it may immediately sell at an unfavorable price.
Another heir may assume the metal can never decline and hold an excessive concentration.
Neither approach reflects informed decision-making.
Families can explain why the gold was purchased, what role it serves, and how it fits within the broader portfolio.
Heirs should also understand dealer premiums, spot prices, selling spreads, storage, insurance, and taxes.
This education does not require future generations to follow exactly the same strategy.
Instead, it gives them enough information to make thoughtful decisions based on their own circumstances.
Gold Should Not Replace Productive Assets
Gold can preserve and diversify wealth, but productive assets remain important.
Stocks represent businesses that can generate earnings.
Property may generate rental income.
Bonds can produce interest.
Private businesses can create profits and employment.
Physical gold produces no cash flow.
Therefore, an excessively large gold allocation may reduce the family’s ability to compound wealth through productive investments.
A balanced generational wealth with gold plan should recognize this trade-off.
Gold can provide a durable reserve asset while businesses, equities, property, and other investments support growth and income.
The objective is not to choose between preservation and growth.
Strong long-term planning usually requires both.
Gold and Silver Can Serve Different Purposes
Families interested in precious metals may also consider silver.
Silver has monetary history and investment demand, but industry plays a much larger role in its modern market.
Manufacturers use silver in electronics, solar technologies, automobiles, electrical systems, and other applications.
This industrial exposure can create strong upside during favorable economic conditions.
However, silver is generally more volatile.
It also requires significantly more storage space for an equivalent dollar value.
Gold may therefore be more practical when the primary goal involves compact long-term wealth storage.
Silver can still complement it for investors comfortable with greater volatility and additional industrial exposure.
Avoid Collectibles Unless You Understand Them
Not every gold product is valued only for its metal content.
Rare coins and collectible products may include substantial numismatic premiums.
Their value can depend on rarity, condition, historical significance, and collector demand.
That creates additional complexity for heirs.
Someone unfamiliar with numismatics may sell a rare coin based only on its gold content and lose much of its collectible value.
Families focused mainly on generational wealth with gold may prefer straightforward bullion products that are easier to understand and value.
Investors who choose collectibles should maintain detailed records and ensure future beneficiaries understand what they own.
Specialist appraisal may also be appropriate.
Buy From Reputable Sources
Counterfeit products create an obvious risk.
Families planning to hold bullion for decades should prioritize authenticity and documentation.
Reputable dealers typically provide clear product information and established purchasing processes.
Investors should understand the weight, purity, manufacturer, and relevant identifying characteristics of each product.
Unusually cheap gold deserves caution.
A price substantially below normal market value may indicate additional risk.
Saving a small amount during the original purchase is not worthwhile if heirs later discover that the product is difficult to authenticate or sell.
Trustworthy sourcing strengthens a long-term precious metal plan.
Understand Premiums and Selling Spreads
The spot gold price is not necessarily the price an investor pays.
Physical bullion usually sells at a premium.
Dealers also need a margin when purchasing metal back from customers.
Therefore, an investor may buy above spot and later sell below the retail price.
These transaction costs matter.
Suppose gold’s market price rises slightly after purchase.
The investor could still have a negative net return because the increase does not cover the original premium and selling spread.
Families building generational wealth with gold should therefore focus on total ownership economics rather than only the quoted spot price.
Comparing products and reputable dealers can help control unnecessary costs.
Taxes Can Affect the Final Inheritance
Tax treatment varies by jurisdiction.
Gold may face capital gains taxes, inheritance taxes, estate taxes, reporting requirements, or other rules depending on where the owner and beneficiaries live.
The ownership structure can also matter.
Physical bullion may receive different treatment from funds, mining shares, or other gold-related investments.
Because rules can change, families should avoid assuming that a strategy used decades earlier will remain optimal.
Periodic reviews with qualified professionals may help.
Tax planning should support legal compliance and efficient wealth transfer.
The important point is simple: the value heirs ultimately keep may differ from the market value of the gold itself.
Liquidity Matters Across Generations
Gold is widely traded, but families still need liquidity outside precious metals.
Unexpected expenses can arise before and after an inheritance.
Property repairs, healthcare, education, taxes, legal costs, and everyday living expenses require cash.
If a family keeps too much wealth in physical bullion, heirs may be forced to sell during an unfavorable market.
Maintaining suitable cash and liquid financial assets can reduce that pressure.
Gold then remains a strategic holding rather than an emergency funding source.
This separation can improve the durability of a generational wealth with gold plan.
Rebalancing Can Protect Against Concentration
Suppose gold represents a modest portion of family wealth today.
Then gold prices rise dramatically for several years.
The position may become much larger than originally intended.
That changes the portfolio’s risk profile.
Rebalancing can restore the desired allocation.
Some gold can potentially be sold, while capital moves toward underrepresented assets.
The reverse may occur after a prolonged gold decline.
Periodic reviews help families maintain the original purpose of each asset.
Without rebalancing, a diversification strategy can gradually become a concentrated bet.
This principle becomes particularly important when assets are intended to remain in a family portfolio for decades.
Do Not Build a Legacy Around Fear
Gold marketing sometimes relies heavily on fear.
Investors may hear predictions of currency collapse, banking failure, hyperinflation, or permanent stock market destruction.
Some risks deserve serious consideration.
However, nobody can predict the future with certainty.
Building most family wealth around one catastrophic scenario creates a different type of vulnerability.
If productive assets perform strongly for decades, an excessively defensive portfolio may sacrifice substantial growth.
Therefore, generational wealth with gold should prepare for uncertainty rather than assume disaster is inevitable.
Diversification provides exposure to several possible futures.
Think Beyond One Generation
True generational planning extends beyond deciding what happens immediately after death.
Families can consider how assets might remain useful for grandchildren and later generations.
This requires governance.
Who makes investment decisions?
How will beneficiaries receive assets?
Should some wealth remain invested collectively?
What financial education will younger family members receive?
Larger estates may use trusts, family investment structures, or professional advisers.
Smaller families can still create clear instructions and organized records.
The complexity should match the size and needs of the estate.
The central goal remains continuity.
Assets become more useful when future generations understand both their value and their intended purpose.
Create a Family Precious Metal Inventory
An organized inventory can simplify long-term management.
The inventory can record each gold product, weight, purity, purchase date, purchase cost, and relevant documentation.
It should also note whether the asset has been sold or transferred.
However, families should protect this information carefully.
A detailed bullion inventory can create security risks if it reaches unauthorized people.
Therefore, financial records and physical storage information may need different levels of protection.
Authorized estate representatives should know how to access necessary information.
Regularly updating the inventory can prevent confusion as holdings change.
Review the Plan After Major Life Events
A long-term legacy strategy should evolve.
Marriage, divorce, births, deaths, relocation, business sales, retirement, and major inheritances can all change estate planning needs.
Tax rules can change as well.
Storage arrangements that worked when an investor was younger may become inconvenient later.
Beneficiary relationships may also evolve.
Therefore, families should periodically review generational wealth with gold alongside the rest of the estate.
Reviews do not require constant changes.
Instead, they confirm that ownership, beneficiaries, documentation, storage, and allocation still match current goals.
Common Mistakes Families Should Avoid
Several mistakes can undermine a gold legacy.
The first is keeping bullion secret from everyone.
Privacy is valuable, but complete secrecy can cause assets to disappear from the estate.
Another mistake is failing to keep purchase records.
Families may also buy complicated collectibles without documenting their additional value.
Excessive concentration creates another risk.
Gold should not automatically replace productive assets.
Poor storage can expose physical metal to theft.
Finally, families sometimes focus entirely on accumulating wealth while providing no financial education to heirs.
Successful inheritance requires both assets and knowledge.
A Simple Gold Legacy Framework
Families can build a straightforward process.
First, define why gold belongs in the family portfolio.
Next, determine an allocation that complements other investments.
Choose recognizable bullion products from reputable sources.
Develop a secure storage arrangement.
Maintain an updated inventory and purchase records.
Include the assets within formal estate planning.
Ensure an appropriate executor, trustee, or trusted representative can locate the necessary information.
Educate beneficiaries about gold’s purpose, risks, transaction costs, and role within the broader portfolio.
Finally, review the strategy periodically.
This structure makes generational wealth with gold a deliberate financial plan rather than simply a collection of bullion.
Conclusion
Gold can play a meaningful role in building a financial legacy, but owning bullion alone does not create generational wealth.
The metal offers several useful characteristics. It is durable, globally recognized, compact, and driven by different forces from many traditional financial assets.
These qualities can make it valuable for diversification and long-term wealth planning.
However, gold does not generate regular income. Its price can decline, and physical ownership introduces storage, security, transaction, tax, and inheritance considerations.
Therefore, generational wealth with gold works best when it complements productive assets such as businesses, equities, property, and other investments.
Documentation is equally important.
Heirs need to know what exists, how ownership is structured, and how authorized access works. Financial education can also help future generations manage inherited assets responsibly.
Ultimately, successful generational wealth with gold is not simply about passing down ounces of metal. It is about creating a diversified, documented, secure, and understandable financial legacy that future generations can manage according to their own needs and opportunities.
FAQ
1. Is Gold Good for Passing Wealth to Children?
Gold can be useful because it is durable, globally recognized, and relatively compact. However, proper documentation, secure storage, estate planning, and diversification remain essential.
2. Should Families Buy Gold Coins or Bars?
Both can work. Bars may offer efficient exposure, while smaller coins or bars can sometimes be easier to divide among beneficiaries. Premiums and authenticity should also be considered.
3. Should Heirs Keep or Sell Inherited Gold?
That depends on their financial goals, portfolio, liquidity needs, taxes, and risk tolerance. Families can educate heirs about the asset without requiring them to keep it permanently.
4. Can Gold Replace Property and Stocks in a Family Legacy?
Gold serves a different purpose. Property and businesses can generate income, while stocks provide exposure to corporate growth. Diversification may be more appropriate than relying entirely on one asset.
5. How Can Families Prepare Gold for Inheritance?
Keep accurate records, use secure storage, include bullion in formal estate planning, and ensure authorized representatives can locate necessary information. A strong generational wealth with gold strategy should make the assets secure but accessible to legitimate heirs.